

The Price of a View: Dubai Apartment Yields by Floor & Vista
A data-driven analysis of how an apartment's view and floor level impact its rental income, purchase price, and ultimate net yield in Dubai's competitive market.

Every investor I meet wants to know the secret to maximising rental yield. They ask about location, amenities, and payment plans. But the question that contains the most nuance, and often the most money, is about the unit itself: how much is a view really worth? It’s a simple question with a complex, numbers-driven answer that separates speculative buyers from strategic landlords. This isn't about aesthetics; it's a quantitative exercise in floor level yield analysis.
Here's what we'll explore in detail:
- The fundamental flaw in chasing gross rent and why net yield is the only metric that matters.
- A breakdown of Dubai's iconic views — sea, landmark, marina, and community, and the rental premiums they command.
- The floor-by-floor dynamic: the real impact of low, mid, high, and penthouse levels on your income.
- The numbers, line-by-line: Two detailed case studies calculating the net yield for apartments with different views and purchase prices.
- The short-term let factor: how holiday rentals amplify the value of a premium view.
- My final verdict on whether paying millions more for a better vista is a smart investment strategy.
The Premium View Myth: Gross Rent vs. Net Yield
As a rental yield analyst, the most common mistake I see investors make is conflating high rent with a great investment. A real estate agent might tell you, “This apartment on the 60th floor with a full Burj Khalifa view rents for AED 200,000,” while a similar unit on the 10th floor facing the community rents for AED 150,000. The immediate conclusion for many is that the 60th-floor unit is the superior asset. It generates more income, after all. This is a dangerously incomplete picture. The critical question isn't *what it rents for*, but *what you paid for it* and *what it costs you to hold*. This is the core of any serious floor level yield analysis.
The entire concept of a rental premium for a view or a high floor is built on this incomplete truth. Yes, tenants will pay more for a better view. The Dubai apartment view premium is a real, tangible market force. An apartment in Dubai Marina with a full water view will always rent for more than an identical one facing the road. But the developer or the seller on the secondary market knows this, too. They have already priced that future rental premium into your purchase price. The premium you pay upfront can often be far greater than the rental uplift you can realistically achieve, which crushes your net yield.
Let’s define our terms precisely. Gross yield is simply the annual rental income divided by the property’s purchase price. It’s a quick, back-of-the-envelope calculation, but it ignores all the real-world costs of being a landlord. Net yield is where the truth lies. It takes your gross rental income and subtracts all your annual running costs — service charges, maintenance, property management fees, and potential void periods, before dividing by your total investment cost, which includes the purchase price plus all associated fees like the 4% Dubai Land Department (DLD) transfer fee and agent commissions. This is the figure that tells you what the property is actually earning for you.
When we apply this logic, the 'obvious' choice of the high-floor, premium-view unit starts to look less certain. If the Burj-view apartment cost you AED 4 million and the community-view unit cost AED 2.5 million, the underlying maths changes dramatically. The higher purchase price for the premium view acts as a dead weight on your yield calculation from day one. Your goal as an investor isn't to own the most impressive apartment; it's to own the most profitable one. Sometimes those are the same thing, but frequently, they are not. The rest of this analysis will be dedicated to finding that profitable sweet spot.
A Hierarchy of Views: Deconstructing the Dubai Rental Premium
 Featured project
Not all views are created equal, and in Dubai, we have a very clear and established hierarchy. The premium a view commands is a direct function of its rarity, dynamism, and iconic status. Understanding this pecking order is essential for any investor looking to make an informed decision. The financial impact of specific views on rental income is significant and predictable, provided you know what to look for. Let's break down the main categories.
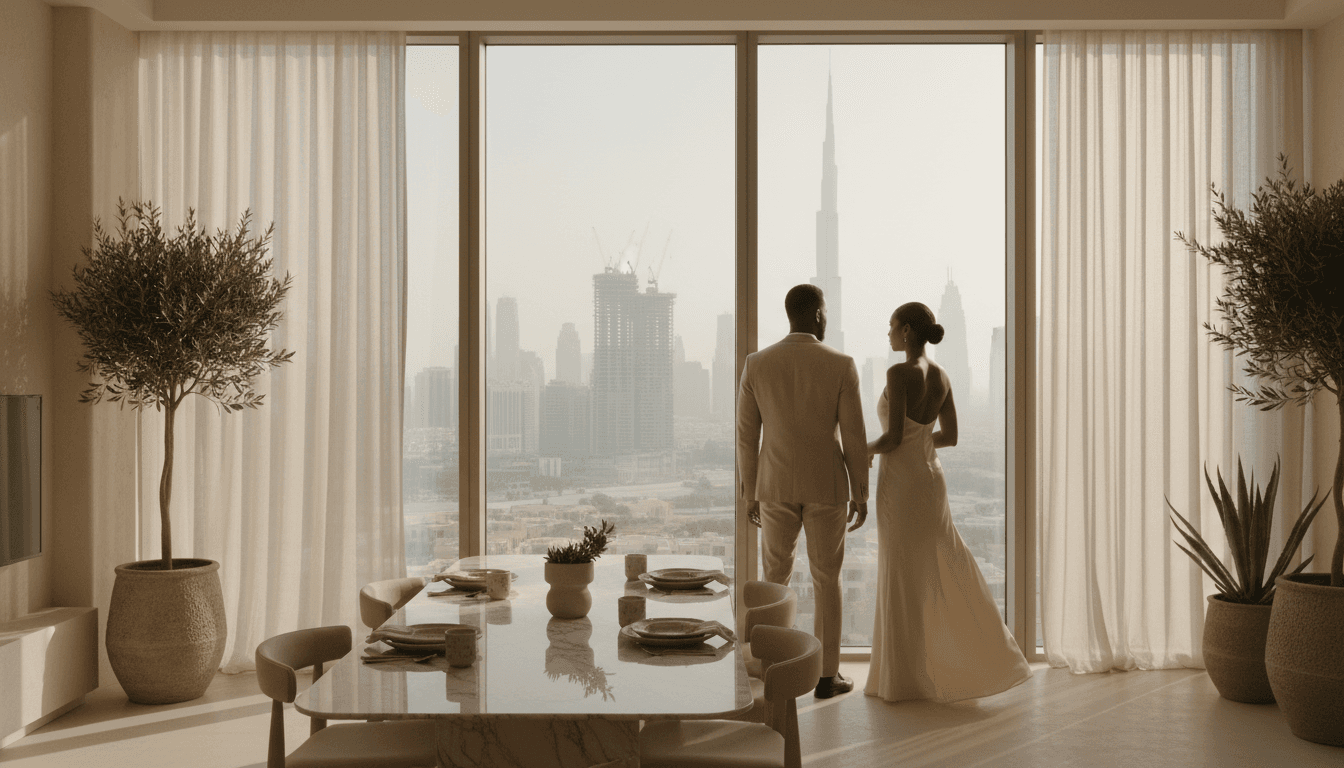
At the absolute top of the pyramid are the 'Triple Prime' views: a direct, unobstructed, high-floor view of the sea, a world-famous landmark, or a vibrant water body like the Marina. The ultimate example is a front-facing apartment in Emaar Beachfront or a high-floor unit on Palm Jumeirah looking back at the Marina skyline. These views are not just pleasant; they are global trophies. For long-term rentals, you can expect a premium of 25-40% compared to a unit in the same building with a partial or community view. In the short-term market, this premium can be even higher. The key here is 'unobstructed'. A partial sea view between two other buildings is a completely different asset class from a panoramic, front-row vista.
Next in the hierarchy is the 'Landmark View'. This is primarily defined by a clear line of sight to the Burj Khalifa, especially one that includes the Dubai Fountain. An apartment in Downtown or Business Bay with this view can command a 20-35% rental premium. The New Year's Eve fireworks display alone makes these units incredibly valuable for both long-term tenants and short-term lets. Other landmark views are emerging, such as a direct view of the Ain Dubai from Bluewaters or JBR, or the future Dubai Creek Tower from Creek Harbour. These are powerful rental drivers because they offer tenants a tangible piece of the 'Dubai dream' — a view that is instantly recognisable and impressive.
Moving down a tier, we find 'Active Views'. This includes the golf course views in communities like Emirates Hills or Damac Hills, and the full marina views from within Dubai Marina. These are highly desirable because they offer a sense of life and activity. Tenants enjoy watching the yachts go by or the green expanse of the course. These views typically add a 15-25% rental premium over a standard road or building view. They offer a feeling of space and nature, which is a significant plus in a dense urban environment. Finally, we have the 'Community and Park Views'. In master-planned communities like JVC or Town Square, an apartment overlooking the central park or a landscaped garden is more desirable than one facing a busy road or an adjacent building. The premium here is more modest, typically in the 5-15% range, but it's consistent and contributes to lower vacancy rates. These views appeal to end-users, particularly families, who value the peaceful and green environment.
The Vertical Axis: How Floor Level Impacts Rent and Value
The horizontal axis of real estate is location, but in a city of skyscrapers like Dubai, the vertical axis — the floor level, is just as critical to your investment analysis. The relationship between floor number and rental income isn't linear; it's a curve with distinct zones, each with its own characteristics, target tenants, and investment logic. Simply assuming 'higher is better' is a lazy analysis that will cost you yield. A sophisticated high floor rental yield strategy requires a more granular approach.
Let's divide a typical high-rise building into three zones. First, the 'Low Floors' (roughly floors 1-9). The conventional wisdom is that these are the least desirable. They can suffer from noise from street level, have obstructed views, and may feel less private. Consequently, they are priced the lowest, both for sale and for rent. However, this is where a savvy investor can find opportunities. A low-floor apartment with a large terrace or direct access to the swimming pool can be exceptionally popular with families or tenants who value convenience over a panoramic view. Because the purchase price is significantly lower, the low floor impact on rent, while negative, may be less severe than the impact of the lower capital outlay on your yield calculation. In short, a 10% reduction in rent on a unit that cost 20% less to buy can lead to a superior net yield.
Next, we have the 'Mid Floors' (roughly floors 10-30). This is often the sweet spot for a balanced investment. You are high enough to clear the noise and obstructions of the ground level, and the views begin to open up. You might gain a partial sea or skyline view that wasn't visible from lower down. Tenants appreciate this elevation, and a tangible rental premium of 5-15% over the low floors is realistic. Critically, the purchase price premium for a mid-floor unit over a low-floor one is often more moderate than the jump to the true high floors. This balance makes mid-floor units a strong, stable choice for yield-focused investors. They offer a good portion of the benefits of a high floor without the exorbitant entry cost.
Finally, the 'High Floors' and 'Penthouse Levels' (anything above floor 30, and especially 50+). This is the trophy asset category. Here, you get the expansive, panoramic views that define luxury Dubai living. The air is clearer, the noise is gone, and the sense of exclusivity is palpable. The rental premium is significant, often 15-25% or more above a mid-floor unit. However, the purchase price premium is astronomical. Developers and sellers charge disproportionately for these 'sky villas'. The investment case here is often less about rental yield and more about capital appreciation and status. The pool of tenants who can afford the rent on a 70th-floor penthouse is also much smaller, potentially leading to longer vacancy periods between tenancies. While the gross rent is impressive, the net yield can often be lower than that of a well-chosen mid-floor apartment.
Case Study 1: The Premium View in Dubai Marina
To move from theory to practice, let's run the numbers on a real-world scenario. We'll analyse two comparable two-bedroom apartments in the same tower in Dubai Marina. This allows us to isolate the variables of view and floor level while keeping the building's quality, amenities, and location constant.
- Unit A: A mid-floor (15th) two-bedroom apartment (1,200 sq. Ft.) with a partial view of the road and adjacent buildings.
- Unit B: A high-floor (45th) two-bedroom apartment (1,200 sq. Ft.) in the same building with a full, unobstructed view of the marina and the sea.
First, the purchase price. Based on current market data, Unit A might be priced at AED 2,500,000. Unit B, with its premium view and floor, commands a significantly higher price, let's say AED 3,500,000. That's a 40% premium for the better position. Now let's look at the total acquisition cost, which is the number we must use for our yield calculation. This includes the DLD transfer fee and other associated costs.
Total Investment Cost Breakdown: - Unit A (Standard View): - Purchase Price: AED 2,500,000 - DLD Fee (4%): AED 100,000 - Agency Fee (~2%): AED 50,000 - Trustee & Reg Fees: AED 5,000 - Total Investment: AED 2,655,000
- Unit B (Premium View):
- Purchase Price: AED 3,500,000
- DLD Fee (4%): AED 140,000
- Agency Fee (~2%): AED 70,000
- Trustee & Reg Fees: AED 5,000
- Total Investment: AED 3,715,000
Now, let's analyse the rental income and expenses. Unit A, with its standard view, realistically rents for AED 150,000 per year. Unit B, with its stunning vista, can achieve a much higher rent, say AED 195,000 per year. That's a 30% rental premium. On the surface, Unit B looks great. But we need to calculate the net yield. Let's assume annual service charges are AED 20 per sq. Ft. (so AED 24,000 per year for both units), and we budget a 5% property management fee on the rental income.
Net Yield Calculation: - Unit A (Standard View): - Gross Rent: AED 150,000 - Service Charges: -AED 24,000 - Management Fee (5%): -AED 7,500 - Net Annual Income: AED 118,500 - Net Yield: (AED 118,500 / AED 2,655,000) = 4.46%
- Unit B (Premium View):
- Gross Rent: AED 195,000
- Service Charges: -AED 24,000
- Management Fee (5%): -AED 9,750
- Net Annual Income: AED 161,250
- Net Yield: (AED 161,250 / AED 3,715,000) = 4.34%
This is the kind of result that surprises many investors. Despite generating AED 45,000 more in gross rent per year, the premium view apartment (Unit B) delivers a *lower* net yield. The 40% purchase price premium was not fully compensated by the 30% rental uplift. In this scenario, the investor in Unit A, the 'lesser' apartment, has made the more efficient, higher-yielding investment. The extra million dirhams paid for the view was, from a pure yield perspective, a misallocation of capital.
Case Study 2: The Community View in JVC
Let's run the same analysis in a different market segment to see if the principle holds. We'll move to Jumeirah Village Circle (JVC), a community known for its affordability and popularity with young professionals and families. Here, the view premium is more subtle, often revolving around proximity to a park versus a main road.
- Unit C: A low-floor (3rd) one-bedroom apartment (800 sq. Ft.) facing a busy internal road.
- Unit D: A mid-floor (12th) one-bedroom apartment (800 sq. Ft.) in the same building, overlooking the community park.
In JVC, the price difference will be less dramatic than in the Marina. Unit C, the road-facing apartment, might sell for AED 900,000. Unit D, with the desirable park view, might command a 15% premium, selling for AED 1,035,000. Let's calculate the total investment.
Total Investment Cost Breakdown: - Unit C (Road View): - Purchase Price: AED 900,000 - DLD Fee (4%): AED 36,000 - Agency Fee (~2%): AED 18,000 - Trustee & Reg Fees: AED 5,000 - Total Investment: AED 959,000
- Unit D (Park View):
- Purchase Price: AED 1,035,000
- DLD Fee (4%): AED 41,400
- Agency Fee (~2%): AED 20,700
- Trustee & Reg Fees: AED 5,000
- Total Investment: AED 1,102,100
Now for the income. Unit C might rent for AED 70,000 per year. The park view in Unit D is a strong selling point for tenants in JVC, allowing the landlord to charge around AED 78,000 per year, a rental premium of about 11.4%. Service charges are typically lower in JVC, let's say AED 15 per sq. Ft. (so AED 12,000 per year), and we'll use the same 5% management fee.
Net Yield Calculation: - Unit C (Road View): - Gross Rent: AED 70,000 - Service Charges: -AED 12,000 - Management Fee (5%): -AED 3,500 - Net Annual Income: AED 54,500 - Net Yield: (AED 54,500 / AED 959,000) = 5.68%
- Unit D (Park View):
- Gross Rent: AED 78,000
- Service Charges: -AED 12,000
- Management Fee (5%): -AED 3,900
- Net Annual Income: AED 62,100
- Net Yield: (AED 62,100 / AED 1,102,100) = 5.63%
Once again, the result is incredibly close, but the supposedly inferior, cheaper apartment (Unit C) edges out the premium park-view unit on net yield. The 15% purchase price premium for the park view wasn't quite justified by the 11.4% rental increase it generated. This demonstrates that the principle holds true across different market segments. The lower entry price for the less desirable view often creates a more efficient yield-generating asset, even if the absolute rental income is lower. An investor's capital works harder in the cheaper unit.
“The 'Dubai apartment view premium' is real, but it's often priced so efficiently into the sale price that it neutralises any potential gain in net rental yield for the investor.”
The Short-Term Let Amplifier
So far, our analysis has focused on the long-term rental market, which forms the bedrock of Dubai's residential investment landscape. However, the rise of the short-term rental (holiday home) market introduces a powerful new variable that can dramatically alter our calculations. The dynamics of the short-term rental market place a much heavier emphasis on immediate 'wow' factor, and nothing says 'wow' like a spectacular view.
A long-term tenant, who will live in a property for a year or more, might balance a great view against other factors like space, layout, and proximity to their work. A tourist or business traveller staying for a week is making a much more emotional and impulsive decision. They are buying an experience. Scrolling through listings, the properties with the most dramatic and photogenic views — a panoramic sweep of the sea from Bluewaters Island, the dancing fountains from a Downtown balcony, the yachts in the Marina, are the ones that get clicked and booked. This allows landlords in the short-term market to charge a much higher premium for a view than in the long-term market.
Revisiting our Dubai Marina case study, the 30% annual rental premium for the full marina view might translate into a 50-60% premium on the average *nightly rate*. That stunning view is a powerful marketing tool that directly increases occupancy and revenue. This can fundamentally change the yield equation. Let's imagine both Unit A (standard view) and Unit B (premium view) are operated as holiday homes. Unit A might achieve an average nightly rate of AED 700 with 75% occupancy, while Unit B, with its superior view, could command AED 1,100 per night with 80% occupancy due to higher demand.
This would result in a gross annual income of approximately AED 191,625 for Unit A, and a staggering AED 321,200 for Unit B. When you factor in the higher costs associated with short-term lets (higher management fees, furnishing costs, utility bills, maintenance), the net income gap remains substantial. In this scenario, the much higher income from Unit B could be enough to overcome its higher purchase price and deliver a superior net yield compared to Unit A. Therefore, for investors specifically targeting the holiday home market, paying the premium for a trophy view can be a very shrewd and profitable strategy. It's a different business model that requires a different approach to asset selection. The key is to commit to one strategy; a property chosen for long-term yield may not be optimal for short-term lets, and vice versa.
My Verdict: Where Should You Invest?
After running the numbers and analysing the market from multiple angles, my conclusion is nuanced. There is no single 'best' strategy that fits every investor. The right choice depends entirely on your goals, capital, and risk appetite. However, we can draw some clear, actionable insights from this analysis.
For the pure, yield-focused long-term investor, my advice is almost always to forego the trophy view. The data consistently shows that the purchase price premium for a stunning view or a penthouse-level floor often outweighs the achievable rental premium, leading to a compressed or even lower net yield. Your capital is often more efficient when deployed in a less glamorous, but more mathematically sound, asset. The sweet spot for long-term holds is often a mid-floor unit in a good building, or even a well-located low-floor unit with a practical advantage like a large terrace. You sacrifice the bragging rights, but you win on the spreadsheet, which is what matters in investing.
This doesn't mean you should buy an apartment with a terrible view, facing a wall or a noisy highway. A baseline level of quality is essential to attract and retain good tenants. The goal is to find the point of diminishing returns — the point where paying more for a better view no longer generates a proportional increase in net yield. In my experience, this point is reached much faster than most buyers assume. A solid community view, a partial sea view, or a view over a park often provides the best balance of rental appeal and capital efficiency.
For long-term rental investors, the most profitable strategy is often to buy the 'worst' view in the 'best' building or community. You benefit from the location and amenities without overpaying for a premium vista whose cost negates the extra rent. The opposite is true for the short-term holiday market, where a 'trophy' view is a key asset that can drive significantly higher nightly rates and occupancy, justifying its high purchase price.
Ultimately, property value is determined by more than just views. Factors like the developer's reputation — a known quantity like Emaar Properties or Nakheel, the quality of building management, and future infrastructure development in the area are all critical. Before making any decision, you must do the maths yourself. Build a spreadsheet. Input the total purchase cost, the realistic rental income, and all the annual expenses. Compare the net yield of the premium unit against the standard one. The numbers will not lie. At Gaia Living, this is the analytical rigour we bring to every client consultation. An investment decision based on a postcard view is a holiday; one based on a net yield calculation is a business.
## Sources - Dubai Land Department (DLD) - for transfer fee information and procedures: dubailand.gov.ae - Real Estate Regulatory Agency (RERA) - for service charge index and rental regulations: dubailand.gov.ae - The Official Portal of the UAE Government - for general legal and residency information: u.ae
Questions, answered
- How much more rent can I charge for a Burj Khalifa view in Dubai?
- A full, unobstructed Burj Khalifa view can command a 20-35% rental premium over a standard unit in the same building. However, the purchase price premium is often higher, meaning your net yield may not increase proportionally.
- Does a higher floor always mean higher rent in Dubai?
- Generally, yes. Mid-floor apartments (floors 10-30) often see a 5-10% rental lift over low floors. High floors (30+) can see a 10-20% premium, but this is highly dependent on the quality of the view that opens up at that elevation.
- Which apartment view provides the best rental yield in Dubai?
- In my analysis, a mid-to-high floor apartment with a clear water view (e.g., Dubai Marina or Creek Harbour) often hits the sweet spot. It provides a significant rental premium that is not entirely erased by an excessive purchase price, leading to a strong net yield.
- Is a low-floor apartment a bad investment?
- Not at all. Low-floor apartments with direct access to amenities like pools or parks can be very attractive to families. They typically have a lower purchase price, and while the rent is less than high-floor units, the net yield can be very competitive and stable.
- How do service charges affect the yield of a premium view apartment?
- Service charges in Dubai are calculated per square foot and are the same for all units of the same size in a building, regardless of view or floor. This means the higher rent from a premium view directly improves your income without increasing this specific cost, positively impacting your net yield calculation.
- Does the view premium hold up in the short-term rental market?
- Yes, even more so. The 'wow' factor of a prime view (sea, Ain Dubai, Burj Khalifa) is a major driver for holiday lets and can justify significantly higher nightly rates, often pushing the gross yield into double digits. However, this comes with higher management costs and vacancy risks.
Marcus is all about cash flow — gross vs net yields, short-term vs long-term lets, and the RERA rental index. He writes for landlords and income investors.
Related stories
Choosing Your Dubai Home: A Guide to Property Types
I'll walk you through the key differences between apartments, villas, townhouses, and branded residences in Dubai, helping you match the right property to your lifestyle and financial goals.
Dubai's Niche Off-Plan: The Liquidity Test
Unique off-plan properties promise distinction, but their specialised nature can pose significant resale challenges. I analyse how to assess the long-term liquidity of these investments before you commit.
The FX Effect: Currency Shifts and Dubai Property
A deep dive into how fluctuating Sterling and Ruble values are reshaping purchasing power and investment strategies for British and Russian buyers in Dubai's real estate market.
Echoes, in your inbox
One thoughtful email a month. Market insight, new launches, no spam.